Description
The U.S. Sector strategy allocates dynamically between four long U.S. sector sub-strategies. Each of the four long sub-strategies use different momentum and mean reversion criteria
Due to the low correlation of these strategies, the combination creates a strategy with a considerably higher Sharpe Ratio than a simple sector rotation.
The strategy uses SPDR sector ETFs, but you can replace these with the corresponding sector ETFs or futures from other issuers.
US sectors have historically been good for trend following systems because each sector usually over or under performs for long periods at a time due to longer lasting economic cycles and not just short-term market fluctuations.
The economy itself is not a linear stable system, but swings between periods of expansion (growth) and contraction (recession). This results in a series of market cycles which are visualized in the following picture.
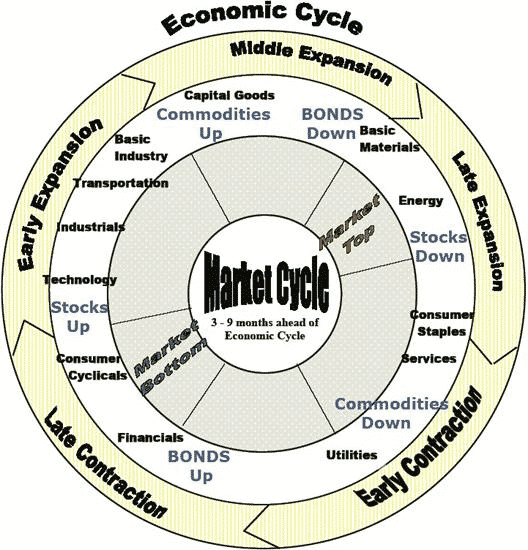
Source: http://www.nowandfutures.com (Global Business Cycles)
Each market cycle favors different industry sectors. The goal of a good working strategy is to choose the best performing sectors while avoiding or even shorting the worst performing sectors.
You can read the original strategy whitepaper for more details.
Methodology & Assets
U.S. industry sectors ETFs, their corresponding inverse or short sector ETFs and optional futures:
| U.S. Sector | ETF | Inverse (leverage) | Globex Futures |
| Materials | XLB | SMN (-2x) | IXB |
| Energy | XLE | ERY (-3x) | IXEe |
| Financial | XLF | SKF (-2x) | IXM |
| Industrials | XLI | SIJ (-2x) | IXI |
| Technology | XLK | REW (-2x) | IXT |
| Consumer Staples | XLP | SZK (-2x) | IXR |
| Real Estate | XLRE | SRS (-2x) | - |
| Utilities | XLU | SDP (-2x) | IXU |
| Health Care | XLV | RXD (-2x) | IXV |
| Consumer Discretionary | XLY | SCC (-2x) | IXY |
Statistics (YTD)
TotalReturn:
'Total return, when measuring performance, is the actual rate of return of an investment or a pool of investments over a given evaluation period. Total return includes interest, capital gains, dividends and distributions realized over a given period of time. Total return accounts for two categories of return: income including interest paid by fixed-income investments, distributions or dividends and capital appreciation, representing the change in the market price of an asset.'
Which means for our asset as example:- Compared with the benchmark SPY (84.5%) in the period of the last 5 years, the total return, or performance of 40.8% of US Sector Rotation Strategy is smaller, thus worse.
- Compared with SPY (78%) in the period of the last 3 years, the total return, or increase in value of 16.8% is lower, thus worse.
CAGR:
'Compound annual growth rate (CAGR) is a business and investing specific term for the geometric progression ratio that provides a constant rate of return over the time period. CAGR is not an accounting term, but it is often used to describe some element of the business, for example revenue, units delivered, registered users, etc. CAGR dampens the effect of volatility of periodic returns that can render arithmetic means irrelevant. It is particularly useful to compare growth rates from various data sets of common domain such as revenue growth of companies in the same industry.'
Using this definition on our asset we see for example:- Looking at the annual performance (CAGR) of 7.1% in the last 5 years of US Sector Rotation Strategy, we see it is relatively lower, thus worse in comparison to the benchmark SPY (13.1%)
- During the last 3 years, the annual performance (CAGR) is 5.3%, which is lower, thus worse than the value of 21.3% from the benchmark.
Volatility:
'In finance, volatility (symbol σ) is the degree of variation of a trading price series over time as measured by the standard deviation of logarithmic returns. Historic volatility measures a time series of past market prices. Implied volatility looks forward in time, being derived from the market price of a market-traded derivative (in particular, an option). Commonly, the higher the volatility, the riskier the security.'
Applying this definition to our asset in some examples:- Looking at the 30 days standard deviation of 11.3% in the last 5 years of US Sector Rotation Strategy, we see it is relatively lower, thus better in comparison to the benchmark SPY (17.2%)
- Looking at volatility in of 8.7% in the period of the last 3 years, we see it is relatively lower, thus better in comparison to SPY (15.3%).
DownVol:
'The downside volatility is similar to the volatility, or standard deviation, but only takes losing/negative periods into account.'
Using this definition on our asset we see for example:- Compared with the benchmark SPY (11.8%) in the period of the last 5 years, the downside deviation of 8.2% of US Sector Rotation Strategy is smaller, thus better.
- During the last 3 years, the downside deviation is 6.2%, which is smaller, thus better than the value of 10.2% from the benchmark.
Sharpe:
'The Sharpe ratio is the measure of risk-adjusted return of a financial portfolio. Sharpe ratio is a measure of excess portfolio return over the risk-free rate relative to its standard deviation. Normally, the 90-day Treasury bill rate is taken as the proxy for risk-free rate. A portfolio with a higher Sharpe ratio is considered superior relative to its peers. The measure was named after William F Sharpe, a Nobel laureate and professor of finance, emeritus at Stanford University.'
Which means for our asset as example:- Compared with the benchmark SPY (0.62) in the period of the last 5 years, the risk / return profile (Sharpe) of 0.41 of US Sector Rotation Strategy is smaller, thus worse.
- Compared with SPY (1.23) in the period of the last 3 years, the ratio of return and volatility (Sharpe) of 0.33 is lower, thus worse.
Sortino:
'The Sortino ratio improves upon the Sharpe ratio by isolating downside volatility from total volatility by dividing excess return by the downside deviation. The Sortino ratio is a variation of the Sharpe ratio that differentiates harmful volatility from total overall volatility by using the asset's standard deviation of negative asset returns, called downside deviation. The Sortino ratio takes the asset's return and subtracts the risk-free rate, and then divides that amount by the asset's downside deviation. The ratio was named after Frank A. Sortino.'
Which means for our asset as example:- Looking at the excess return divided by the downside deviation of 0.56 in the last 5 years of US Sector Rotation Strategy, we see it is relatively lower, thus worse in comparison to the benchmark SPY (0.89)
- During the last 3 years, the ratio of annual return and downside deviation is 0.45, which is lower, thus worse than the value of 1.83 from the benchmark.
Ulcer:
'The Ulcer Index is a technical indicator that measures downside risk, in terms of both the depth and duration of price declines. The index increases in value as the price moves farther away from a recent high and falls as the price rises to new highs. The indicator is usually calculated over a 14-day period, with the Ulcer Index showing the percentage drawdown a trader can expect from the high over that period. The greater the value of the Ulcer Index, the longer it takes for a stock to get back to the former high.'
Which means for our asset as example:- Compared with the benchmark SPY (8.45 ) in the period of the last 5 years, the Ulcer Ratio of 6.68 of US Sector Rotation Strategy is smaller, thus better.
- Compared with SPY (3.3 ) in the period of the last 3 years, the Ulcer Ratio of 4.66 is greater, thus worse.
MaxDD:
'Maximum drawdown measures the loss in any losing period during a fund’s investment record. It is defined as the percent retrenchment from a fund’s peak value to the fund’s valley value. The drawdown is in effect from the time the fund’s retrenchment begins until a new fund high is reached. The maximum drawdown encompasses both the period from the fund’s peak to the fund’s valley (length), and the time from the fund’s valley to a new fund high (recovery). It measures the largest percentage drawdown that has occurred in any fund’s data record.'
Which means for our asset as example:- The maximum reduction from previous high over 5 years of US Sector Rotation Strategy is -16.4 days, which is larger, thus better compared to the benchmark SPY (-24.5 days) in the same period.
- Compared with SPY (-18.8 days) in the period of the last 3 years, the maximum reduction from previous high of -11.7 days is greater, thus better.
MaxDuration:
'The Drawdown Duration is the length of any peak to peak period, or the time between new equity highs. The Max Drawdown Duration is the worst (the maximum/longest) amount of time an investment has seen between peaks (equity highs) in days.'
Using this definition on our asset we see for example:- Compared with the benchmark SPY (488 days) in the period of the last 5 years, the maximum days below previous high of 507 days of US Sector Rotation Strategy is greater, thus worse.
- Compared with SPY (87 days) in the period of the last 3 years, the maximum days below previous high of 270 days is higher, thus worse.
AveDuration:
'The Drawdown Duration is the length of any peak to peak period, or the time between new equity highs. The Avg Drawdown Duration is the average amount of time an investment has seen between peaks (equity highs), or in other terms the average of time under water of all drawdowns. So in contrast to the Maximum duration it does not measure only one drawdown event but calculates the average of all.'
Which means for our asset as example:- Looking at the average days under water of 153 days in the last 5 years of US Sector Rotation Strategy, we see it is relatively larger, thus worse in comparison to the benchmark SPY (118 days)
- Compared with SPY (17 days) in the period of the last 3 years, the average days below previous high of 73 days is higher, thus worse.
Performance (YTD)
Allocations and holdings shown below are delayed by one month.
Register now to get the current trading allocations.
Allocations ()
Returns (%)
- Note that yearly returns do not equal the sum of monthly returns due to compounding.
- Performance results of US Sector Rotation Strategy are hypothetical and do not account for slippage, fees or taxes.
- Results may be based on backtesting, which has many inherent limitations, some of which are described in our Terms of Use.