Description
The U.S. Sector strategy allocates dynamically between four long U.S. sector sub-strategies. Each of the four long sub-strategies use different momentum and mean reversion criteria
Due to the low correlation of these strategies, the combination creates a strategy with a considerably higher Sharpe Ratio than a simple sector rotation.
The strategy uses SPDR sector ETFs, but you can replace these with the corresponding sector ETFs or futures from other issuers.
US sectors have historically been good for trend following systems because each sector usually over or under performs for long periods at a time due to longer lasting economic cycles and not just short-term market fluctuations.
The economy itself is not a linear stable system, but swings between periods of expansion (growth) and contraction (recession). This results in a series of market cycles which are visualized in the following picture.
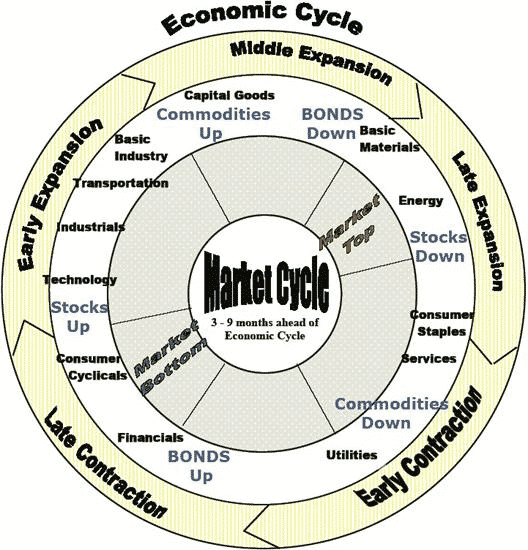
Source: http://www.nowandfutures.com (Global Business Cycles)
Each market cycle favors different industry sectors. The goal of a good working strategy is to choose the best performing sectors while avoiding or even shorting the worst performing sectors.
You can read the original strategy whitepaper for more details.
Methodology & Assets
U.S. industry sectors ETFs, their corresponding inverse or short sector ETFs and optional futures:
| U.S. Sector | ETF | Inverse (leverage) | Globex Futures |
| Materials | XLB | SMN (-2x) | IXB |
| Energy | XLE | ERY (-3x) | IXEe |
| Financial | XLF | SKF (-2x) | IXM |
| Industrials | XLI | SIJ (-2x) | IXI |
| Technology | XLK | REW (-2x) | IXT |
| Consumer Staples | XLP | SZK (-2x) | IXR |
| Real Estate | XLRE | SRS (-2x) | - |
| Utilities | XLU | SDP (-2x) | IXU |
| Health Care | XLV | RXD (-2x) | IXV |
| Consumer Discretionary | XLY | SCC (-2x) | IXY |
Statistics (YTD)
TotalReturn:
'Total return, when measuring performance, is the actual rate of return of an investment or a pool of investments over a given evaluation period. Total return includes interest, capital gains, dividends and distributions realized over a given period of time. Total return accounts for two categories of return: income including interest paid by fixed-income investments, distributions or dividends and capital appreciation, representing the change in the market price of an asset.'
Using this definition on our asset we see for example:- The total return over 5 years of US Sector Rotation Strategy is 41.3%, which is lower, thus worse compared to the benchmark SPY (89.5%) in the same period.
- During the last 3 years, the total return is 16.7%, which is smaller, thus worse than the value of 86.8% from the benchmark.
CAGR:
'The compound annual growth rate isn't a true return rate, but rather a representational figure. It is essentially a number that describes the rate at which an investment would have grown if it had grown the same rate every year and the profits were reinvested at the end of each year. In reality, this sort of performance is unlikely. However, CAGR can be used to smooth returns so that they may be more easily understood when compared to alternative investments.'
Applying this definition to our asset in some examples:- Compared with the benchmark SPY (13.7%) in the period of the last 5 years, the compounded annual growth rate (CAGR) of 7.2% of US Sector Rotation Strategy is smaller, thus worse.
- During the last 3 years, the compounded annual growth rate (CAGR) is 5.3%, which is lower, thus worse than the value of 23.3% from the benchmark.
Volatility:
'In finance, volatility (symbol σ) is the degree of variation of a trading price series over time as measured by the standard deviation of logarithmic returns. Historic volatility measures a time series of past market prices. Implied volatility looks forward in time, being derived from the market price of a market-traded derivative (in particular, an option). Commonly, the higher the volatility, the riskier the security.'
Which means for our asset as example:- The volatility over 5 years of US Sector Rotation Strategy is 11.3%, which is smaller, thus better compared to the benchmark SPY (17.2%) in the same period.
- Compared with SPY (15.3%) in the period of the last 3 years, the 30 days standard deviation of 8.7% is lower, thus better.
DownVol:
'Downside risk is the financial risk associated with losses. That is, it is the risk of the actual return being below the expected return, or the uncertainty about the magnitude of that difference. Risk measures typically quantify the downside risk, whereas the standard deviation (an example of a deviation risk measure) measures both the upside and downside risk. Specifically, downside risk in our definition is the semi-deviation, that is the standard deviation of all negative returns.'
Which means for our asset as example:- Compared with the benchmark SPY (11.8%) in the period of the last 5 years, the downside volatility of 8.2% of US Sector Rotation Strategy is lower, thus better.
- During the last 3 years, the downside risk is 6.2%, which is lower, thus better than the value of 10.2% from the benchmark.
Sharpe:
'The Sharpe ratio (also known as the Sharpe index, the Sharpe measure, and the reward-to-variability ratio) is a way to examine the performance of an investment by adjusting for its risk. The ratio measures the excess return (or risk premium) per unit of deviation in an investment asset or a trading strategy, typically referred to as risk, named after William F. Sharpe.'
Using this definition on our asset we see for example:- Looking at the Sharpe Ratio of 0.42 in the last 5 years of US Sector Rotation Strategy, we see it is relatively smaller, thus worse in comparison to the benchmark SPY (0.65)
- During the last 3 years, the risk / return profile (Sharpe) is 0.32, which is lower, thus worse than the value of 1.36 from the benchmark.
Sortino:
'The Sortino ratio, a variation of the Sharpe ratio only factors in the downside, or negative volatility, rather than the total volatility used in calculating the Sharpe ratio. The theory behind the Sortino variation is that upside volatility is a plus for the investment, and it, therefore, should not be included in the risk calculation. Therefore, the Sortino ratio takes upside volatility out of the equation and uses only the downside standard deviation in its calculation instead of the total standard deviation that is used in calculating the Sharpe ratio.'
Using this definition on our asset we see for example:- The excess return divided by the downside deviation over 5 years of US Sector Rotation Strategy is 0.57, which is smaller, thus worse compared to the benchmark SPY (0.95) in the same period.
- Compared with SPY (2.04) in the period of the last 3 years, the ratio of annual return and downside deviation of 0.45 is smaller, thus worse.
Ulcer:
'The Ulcer Index is a technical indicator that measures downside risk, in terms of both the depth and duration of price declines. The index increases in value as the price moves farther away from a recent high and falls as the price rises to new highs. The indicator is usually calculated over a 14-day period, with the Ulcer Index showing the percentage drawdown a trader can expect from the high over that period. The greater the value of the Ulcer Index, the longer it takes for a stock to get back to the former high.'
Using this definition on our asset we see for example:- Looking at the Ulcer Index of 6.71 in the last 5 years of US Sector Rotation Strategy, we see it is relatively lower, thus better in comparison to the benchmark SPY (8.45 )
- Compared with SPY (3.23 ) in the period of the last 3 years, the Downside risk index of 4.72 is larger, thus worse.
MaxDD:
'Maximum drawdown measures the loss in any losing period during a fund’s investment record. It is defined as the percent retrenchment from a fund’s peak value to the fund’s valley value. The drawdown is in effect from the time the fund’s retrenchment begins until a new fund high is reached. The maximum drawdown encompasses both the period from the fund’s peak to the fund’s valley (length), and the time from the fund’s valley to a new fund high (recovery). It measures the largest percentage drawdown that has occurred in any fund’s data record.'
Which means for our asset as example:- The maximum drop from peak to valley over 5 years of US Sector Rotation Strategy is -16.4 days, which is larger, thus better compared to the benchmark SPY (-24.5 days) in the same period.
- During the last 3 years, the maximum DrawDown is -11.7 days, which is greater, thus better than the value of -18.8 days from the benchmark.
MaxDuration:
'The Maximum Drawdown Duration is an extension of the Maximum Drawdown. However, this metric does not explain the drawdown in dollars or percentages, rather in days, weeks, or months. It is the length of time the account was in the Max Drawdown. A Max Drawdown measures a retrenchment from when an equity curve reaches a new high. It’s the maximum an account lost during that retrenchment. This method is applied because a valley can’t be measured until a new high occurs. Once the new high is reached, the percentage change from the old high to the bottom of the largest trough is recorded.'
Which means for our asset as example:- Looking at the maximum days below previous high of 507 days in the last 5 years of US Sector Rotation Strategy, we see it is relatively greater, thus worse in comparison to the benchmark SPY (488 days)
- During the last 3 years, the maximum time in days below previous high water mark is 270 days, which is larger, thus worse than the value of 87 days from the benchmark.
AveDuration:
'The Drawdown Duration is the length of any peak to peak period, or the time between new equity highs. The Avg Drawdown Duration is the average amount of time an investment has seen between peaks (equity highs), or in other terms the average of time under water of all drawdowns. So in contrast to the Maximum duration it does not measure only one drawdown event but calculates the average of all.'
Applying this definition to our asset in some examples:- The average days below previous high over 5 years of US Sector Rotation Strategy is 154 days, which is higher, thus worse compared to the benchmark SPY (119 days) in the same period.
- Looking at average time in days below previous high water mark in of 75 days in the period of the last 3 years, we see it is relatively larger, thus worse in comparison to SPY (17 days).
Performance (YTD)
Allocations and holdings shown below are delayed by one month.
Register now to get the current trading allocations.
Allocations ()
Returns (%)
- Note that yearly returns do not equal the sum of monthly returns due to compounding.
- Performance results of US Sector Rotation Strategy are hypothetical and do not account for slippage, fees or taxes.
- Results may be based on backtesting, which has many inherent limitations, some of which are described in our Terms of Use.